
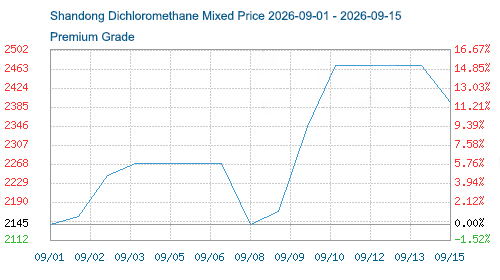
During the first half of September, the dichloromethane market continued the strong upward trend seen since late August; as of September 15, the mixed price for bulk dichloromethane in the Shandong region had risen by 11.66% compared to the beginning of the month.
Analysis of Market Drivers
Cost side: The strong upward movement of both raw materials acts as the primary driver.
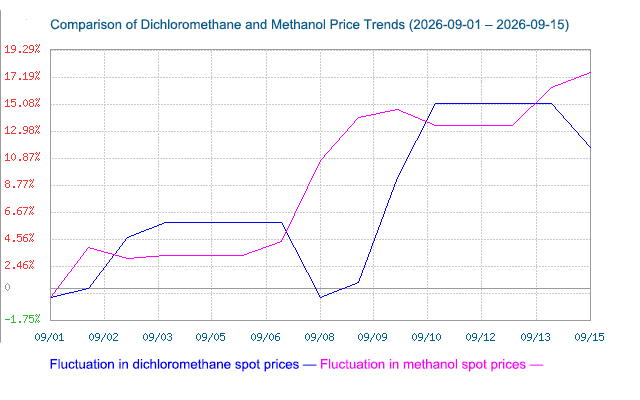
Methanol and liquid chlorine are the direct raw materials for dichloromethane; the simultaneous price increases of both during the first half of September served as the primary driver of the recent market rebound. Methanol prices climbed steadily, rising by over 15% within the two-week period, which directly pushed up dichloromethane production costs. Liquid chlorine prices gradually recovered from approximately 150 yuan/tonne at the start of September, surging by more than 100% over the same period. This rapid rebound in liquid chlorine prices had a significant marginal impact on production costs.
Supply and demand: Supply remains relatively loose, while demand is lackluster.
On the supply side, the operating rate of the chloromethane industry showed a recovery trend during the first half of September. While some major producers had reduced operating loads or shut down for maintenance in August due to losses, there were no significant new maintenance plans for September; furthermore, with expectations for the release of new capacity from Gansu Juhua, overall industry supply remains relatively ample.
On the demand side, while September marked the start of a traditional peak season, actual performance was lackluster. Although demand for R32 refrigerant—a key downstream application—was expected to rise, growth was limited by sluggish end-user consumption; meanwhile, orders from downstream solvent sectors (such as coatings, pharmaceuticals, and agrochemicals) remained weak, with little incentive for proactive restocking. Export demand was also subdued. Following a round of concentrated restocking in early September, the willingness of downstream buyers and traders to take delivery waned by mid-month, as the market’s capacity to absorb higher prices diminished.
Market Outlook
In the short term, with the prices of raw materials—methanol and liquid chlorine—remaining high, cost-side support for price floors stays robust, and manufacturers show no immediate signs of wavering in their resolve to maintain price levels. However, following a rapid surge in early September, prices have reached a cyclical high; downstream resistance to these elevated prices is mounting, and demand-side follow-through has slowed, limiting the scope for further significant gains. The market is expected to undergo narrow-range fluctuations at high levels in the near term as it digests the earlier price increases.
Post time: Sep-16-2026